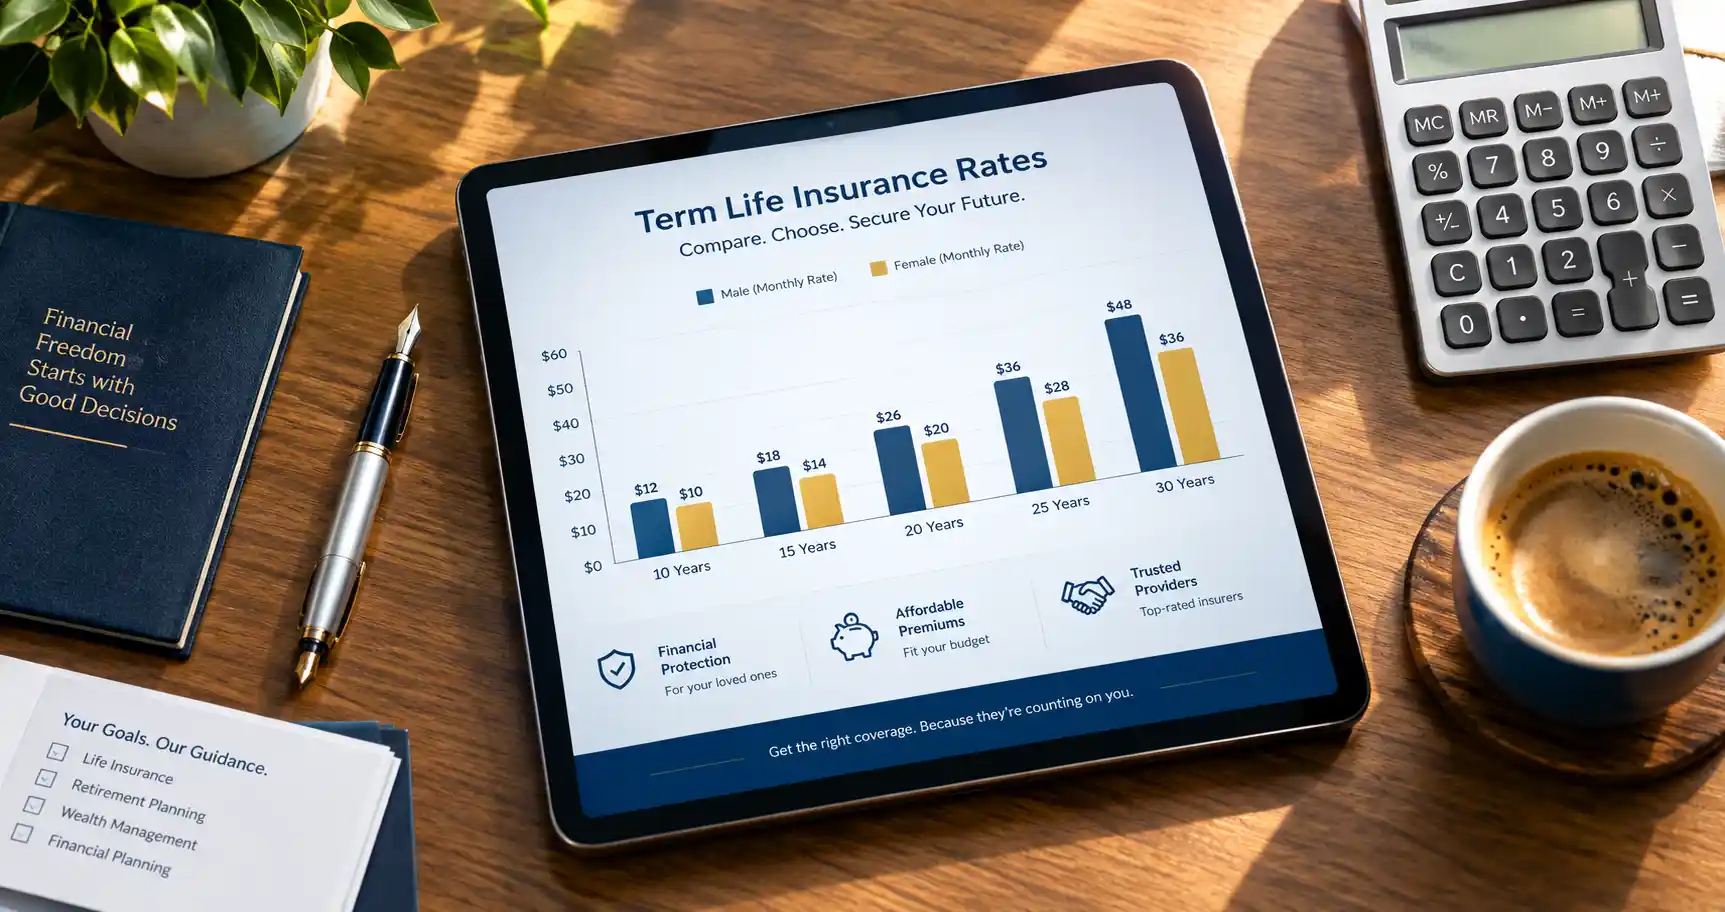
Navigating the 2026 market for term life insurance requires more than just picking the cheapest monthly premium. As economic landscapes and estate tax laws shift, choosing the wrong policy structure can leave your family financially exposed. In my practice as a CPA, I’ve seen too many clients fall into the “term trap.” This guide breaks down exactly how to secure the right coverage without overpaying.
Key Takeaways
- 2026 Average Pricing: A healthy 35-year-old non-smoker can secure a 20-year, $500,000 policy for roughly $25 to $35 per month.
- The “Term Trap” Risk: Buying a 10-year policy at age 30 to save money often backfires; renewal rates at age 40 can spike by over 300% or you may become uninsurable due to new health conditions.
- Living Benefits Context: Modern policies increasingly offer Accelerated Death Benefit riders, though these should be carefully coordinated within your broader estate plan.
Quick Summary: 2026 Term Policies at a Glance
| Policy Feature | Term Life Insurance Details |
| Primary Purpose | Affordable income replacement, mortgage protection, and securing dependents. |
| Policy Duration | Level premium periods of 10, 15, 20, 25, or 30 years. |
| Cash Value Growth | None. You are paying strictly for pure death benefit protection. |
| Tax Implications | Death benefit is generally distributed as a tax-free lump sum to beneficiaries. |
What Is Term Life Insurance?
Many clients ask me, “exactly what is term life insurance and how does it differ from whole life?” In 2026, the definition remains straightforward: it is a pure-protection contract between you and an insurance carrier that guarantees a specific death benefit payout if you pass away during a defined “term” (usually 10 to 30 years). Unlike whole life or universal life policies, there is zero cash value accumulation. You are paying solely for the mortality risk. Because the IRS generally treats the death benefit as an inheritance rather than income, your beneficiaries receive the payout entirely income-tax-free.
Securing Accurate Term Life Insurance Quotes
A major part of my job involves helping clients secure realistic term life insurance quotes. The market is flooded with aggregator sites promising rock-bottom prices, but those teaser rates often assume perfect health, a “Super Preferred” underwriting class, and ignore critical nuances. In reality, a healthy 35-year-old male might pay around $30 a month for a $500,000, 20-year policy, but securing that preferred rate requires passing a rigorous paramedical exam and financial underwriting.
5 Hidden Factors Inflating Your Term Insurance Quotes
When my clients finally sit down with a broker, they are often shocked when their actual term insurance quotes come back 30% higher than the online calculator initially suggested. Here is what is driving up those premiums behind the scenes:
- The MIB Group Report: Insurers pull your Medical Information Bureau file, which tracks past insurance applications and disclosed health conditions.
- Motor Vehicle Records (MVR): A history of DUIs, speeding tickets, or reckless driving instantly bumps you to a higher risk tier.
- Credit-Based Insurance Scores: Your FICO score matters. A low credit score can mathematically signal a higher mortality risk to underwriters.
- Dangerous Hobbies: Avocations like scuba diving, private aviation, or rock climbing require “flat extra” fees added per thousand dollars of coverage.
- Prescription History: Carriers run a script check. Even if your blood pressure is normal today, a history of beta-blockers alerts the underwriter to potential cardiovascular risks.
How to Structure and Select the Best Term Life Insurance
Determining the best term life insurance for your situation goes beyond simply comparing premiums. It requires aligning the policy length with your financial liabilities. I advise my clients to use the “DIME” method (Debt, Income, Mortgage, Education). If your youngest child is 5 and your mortgage is paid off in 20 years, a 20-year term fits perfectly.
Furthermore, if you own a business, you must separate personal and business policies, which often brings up complex tax situations regarding business structure and deductions. To safeguard the death benefit from your own estate taxes, you might need to legally structure the policy ownership within an Irrevocable Life Insurance Trust (ILIT).
Term Life Riders vs. Long Term Care Insurance
A critical distinction for 2026 is understanding living benefits. Many carriers now offer Accelerated Death Benefit riders, allowing you to access a portion of the death benefit while alive if diagnosed with a terminal or chronic illness. However, do not confuse this with standalone long term care insurance. A term rider simply advances your own death benefit and often caps out quickly, whereas a dedicated long-term care policy is legally designed to cover years of specialized facility or nursing care without draining your family’s inheritance.
Pros & Cons of Term Life Policies
Pros:
- Cost-Effectiveness: It is the most affordable way to secure massive death benefit protection during your peak earning and child-rearing years.
- Simplicity: No complex investment sub-accounts, high internal expenses, or fluctuating surrender charges.
- Tax Efficiency: The death benefit transfers to your designated beneficiaries generally free of federal income and estate tax (if properly structured).
Cons:
- Temporary Coverage: If you outlive the level premium period, the policy either expires or the premiums skyrocket annually under a Yearly Renewable Term provision.
- No Wealth Accumulation: Since there is no cash value component, you cannot borrow against the policy or use it as a retirement asset.
- Strict Underwriting: Getting the best rates requires a clean bill of health; pre-existing conditions can result in a “table rating” surcharge or an outright decline.
2026 US Voice Search FAQs
Q: Can I get term life insurance quotes without a medical exam? Yes, many carriers in 2026 offer accelerated no-exam policies that use data algorithms to approve you instantly. However, these policies often charge higher monthly premiums than fully underwritten ones.
Q: What is the average term insurance quote for a 40-year-old? A healthy 40-year-old can expect to pay around $40 to $50 per month for a 20-year, $500,000 policy. Your actual final rate will depend heavily on your detailed medical history and credit-based insurance score.
Q: Does term life insurance cover natural deaths? Yes, term policies cover natural deaths like heart attacks and cancer, provided you did not misrepresent your health on the original application. The only major exclusion is typically a standard suicide clause within the first two years of the policy issuance.
Q: Can I convert my policy into permanent coverage later? Most high-quality policies include a conversion rider that lets you switch to permanent coverage without undergoing another medical exam. You must usually exercise this conversion option before the level term period expires or before you reach a specific age limit.
Q: Is long term care insurance the same as a living benefit rider? No, standalone long term care insurance is designed specifically to pay for extended nursing home and assisted living expenses. A term life living benefit rider simply advances a portion of your own death benefit if you become terminally or chronically ill.
Expert Verdict: Is Term Coverage Right for You?
As a practicing CPA, my final verdict is that term life insurance is the absolute foundation of a responsible financial plan for 95% of American families. You should lock in a level premium that protects your peak earning years and mortgage obligations so your dependents are never left facing financial ruin. While permanent policies have their specific place in complex estate planning, purchasing the best term life insurance gives you the maximum death benefit for the lowest possible cost, allowing you to invest the difference elsewhere. I highly recommend securing your term life insurance quotes from a licensed independent broker today, ensuring they shop across multiple A-rated carriers to find the exact legal and financial structure your family needs.